
Cash flow forecasting predicts exactly when cash will enter and leave your bank accounts over a specified operational timeframe. A reliable cash flow projection tracks liquid balances against timing discrepancies between revenue generation and cash collection. Small business failures rarely stem from inadequate paper profitability; they collapse when liquidity dries up before customer payments clear.
Operating a growing business without an accurate cash projection creates compounding solvency risks. During periods of rapid customer acquisition, inventory purchases and upfront payroll expenditures frequently precede cash collections by 30 to 90 days. Without tactical visibility, healthy revenue growth can rapidly accelerate insolvency.
Core Cash Forecast Formula
Ending Cash = Beginning Cash Balance + Projected Cash Receipts – Projected Cash Disbursements
Where Projected Receipts represent actual cleared bank deposits (not invoiced sales), and Disbursements represent realized debits (not accrued expenses).
The 13-Week Cash Flow Forecast: The Gold Standard for Small Business
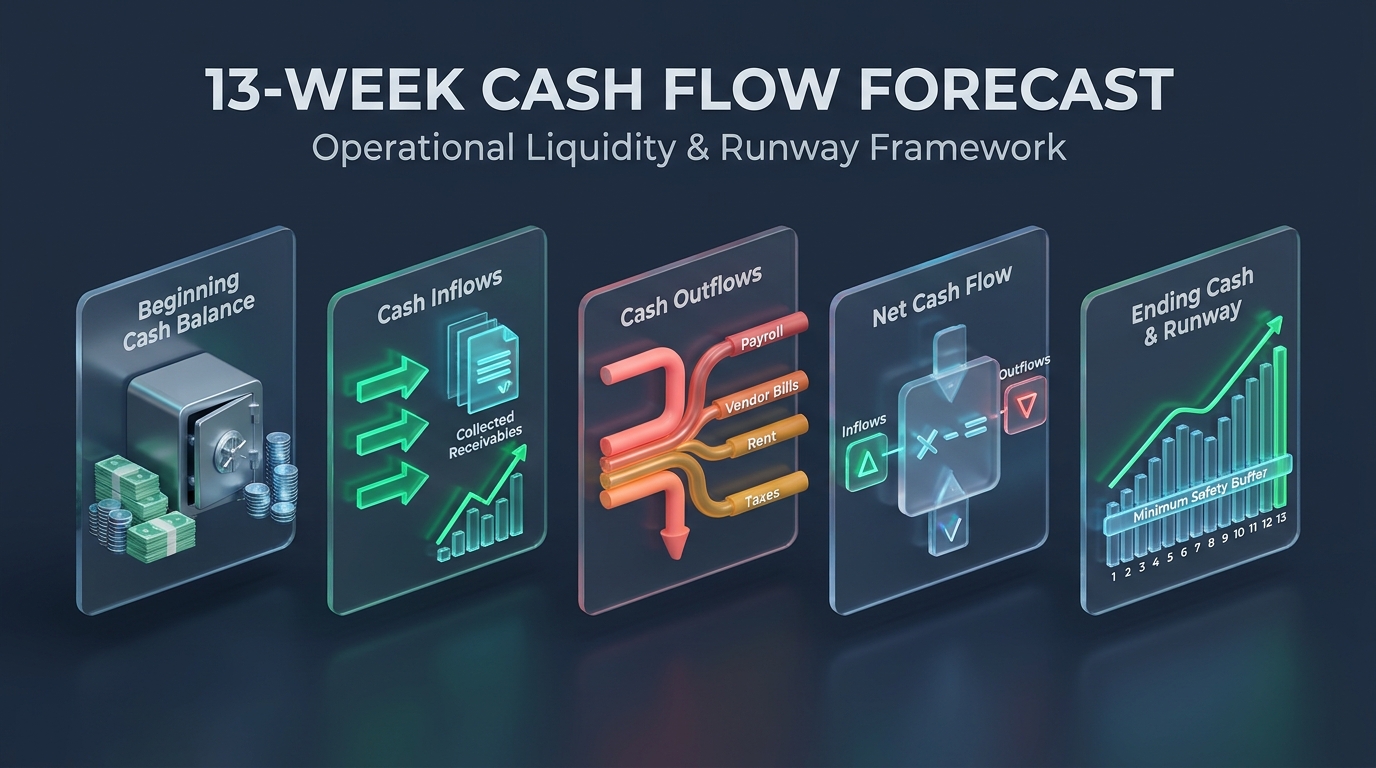
The rolling 13-week cash forecast represents the premier operational liquidity model for small to mid-sized enterprises. Spanning exactly one fiscal quarter, this framework breaks operations down into actionable weekly increments. It bridges high-level annual budgeting with day-to-day accounts payable execution.
Weekly forecasting captures billing friction and payment cycle variance that monthly models completely obscure. Payroll obligations occur bi-weekly or semi-monthly, whereas vendor invoices follow rigid 30-day schedules. Plotting cash movements week by week reveals liquidity deficits weeks before they trigger overdrafts or missed obligations.
Evaluating working capital dynamics alongside cash flow guarantees operational stability. For companies managing complex payroll structures and remote staffing overhead, reviewing our employer of record vs PEO difference guide provides critical insights into optimizing fixed workforce costs. Similarly, e-commerce brands navigating multi-jurisdiction compliance should examine state-level obligations in our economic nexus thresholds compliance guide to accurately model recurring sales tax liabilities.
Direct vs. Indirect Cash Flow Forecasting Methods
Small business operators must deploy the direct cash forecasting method for short-term tactical solvency. The direct method tracks gross cash receipts and disbursements directly from cash accounts and sub-ledgers. In contrast, the indirect method reconciles net income from the income statement by adjusting for non-cash expenses and balance sheet shifts.
| Feature | Direct Forecasting Method | Indirect Forecasting Method |
|---|---|---|
| Core Horizon | 1 to 13 weeks (tactical liquidity) | 6 to 36 months (strategic planning) |
| Primary Data Source | Bank accounts, A/R aging, A/P schedules | Projected P&L and balance sheet line items |
| Accuracy Level | High precision on cash timing & day-to-day variance | Directional estimate of future equity & net debt |
| Operational Use | Payroll funding, vendor payments, inventory buys | Bank covenants, investor reporting, cap-ex planning |
| Maintenance Cadence | Weekly reconciliation and rolling horizon update | Monthly or quarterly strategic review |
Strategic financial reserves often incorporate broader institutional assets and market hedges. Reviewing how public entities structure capital balances in our analysis on US government strategic stock investments highlights institutional liquidity preservation principles during macroeconomic shifts.
Step-by-Step: How to Build Your 13-Week Cash Forecast
Building a durable cash forecast requires disciplined segregation of historical transactions from probabilistic future events. Follow this rigorous 5-step methodology to establish real-time visibility across all operational accounts:
1. Establish Verified Starting Cash
Begin each weekly cycle with verified, reconciled cash across all operational bank accounts. Do not include credit line availability, undeposited funds, or encumbered collateral balances in your opening cash figure. Your beginning cash must reflect immediate liquid buying power as confirmed by real-time bank reconciliation.
2. Forecast Cash Receipts Based on Realized Collection Timing
Project customer cash inflows using historical Days Sales Outstanding (DSO) rather than theoretical invoice terms. If your stated credit terms are Net 30, but client history shows average payments clear in 47 days, schedule cash inflows in the 7th week following billing. Segment cash receipts into three distinct categories: recurring automated subscriptions, historical collections on aged receivables, and projected cash-on-delivery transactions.
3. Map Fixed and Variable Cash Disbursements
Categorize cash disbursements by contractual rigidity and payment frequency. Fixed outflows include payroll, commercial rent, utilities, insurance, software subscriptions, and structured debt amortization. Variable outflows encompass cost of goods sold (COGS), raw material procurement, shipping freight, and discretionary ad spend. Never record accounts payable when billed; record disbursements in the exact week the funds leave your operating account.
4. Calculate Net Weekly Cash and Running Ending Balance
Subtract total weekly cash disbursements from total cash receipts to determine weekly net cash burn or surplus. Add this net figure to your beginning cash balance to calculate the projected ending cash balance. The ending balance of Week 1 automatically populates as the beginning balance for Week 2.
5. Stress-Test with Sensitivity Scenarios
Maintain three distinct forecast variations to protect against operational shocks: Base, Best, and Conservative. Stress-test your model against delayed customer collections, sudden vendor price increases, and unexpected supply chain friction.
| Scenario Model | Revenue Collection Assumptions | Operational Outflow Assumptions | Strategic Action Trigger |
|---|---|---|---|
| Base Case | Historical DSO trends continue (100% baseline) | Scheduled vendor payments and planned payroll | Execute standard operating budget and reinvestment |
| Conservative | DSO slips by 14 days; top 2 accounts delay payment | Vendor payments expedited; emergency repairs added | Freeze non-essential hiring; tap working capital credit line |
| Worst-Case | 30% revenue shock; 60-day enterprise billing delays | Critical debt and payroll prioritized; all capex suspended | Restructure supplier terms; activate contingency cash reserves |
Common Cash Forecasting Traps and How to Avoid Them
Confusing accounting net income with liquid operating cash remains the single most dangerous forecasting error. An enterprise can post a \$50,000 net profit on an accrual basis while sitting on an overdrafted bank balance. Outstanding customer invoices represent book assets, but they cannot settle payroll taxes or vendor invoices.
Failing to budget for lumpy tax payments and quarterly regulatory withholdings also derails growing enterprises. Federal and state estimated income taxes, annual commercial property taxes, and semi-annual insurance premiums arrive at irregular intervals. Standardize these obligations by accruing weekly cash allocations in a segregated reserve account.
Underestimating seasonal fluctuations creates artificial liquidity shortages. Retailers, B2B services, and seasonal contractors experience cyclical invoice volume across calendar quarters. Build seasonal decay rates into your cash receipt modeling to prevent overestimating available cash balances during off-peak periods.
Weekly Cash Forecasting Governance Checklist
Piyush Dwivedi’s Weekly Forecasting Routine
- Monday Morning Reconciliation: Compare prior week’s actual bank balances against forecasted projections to calculate variance.
- Variance Root Cause Analysis: Flag any line items deviating by more than 5% or \$1,000 to identify emerging billing or disbursement trends.
- Rolling Forward: Drop the expired week and add Week 13 to maintain a permanent 90-day visibility window.
- A/R Aging Review: Contact clients with accounts outstanding beyond 35 days and recalibrate projected collection weeks.
- Disbursement Prioritization: Release vendor payables based on strict cash runway priorities rather than arbitrary invoice arrival dates.
What is the difference between a cash flow forecast and a cash budget?
A cash flow forecast predicts future operational cash movements over a rolling timeline to ensure day-to-day liquidity, while a cash budget establishes fixed spending limits allocated across departments for an entire fiscal quarter or year.
How often should a small business update its cash flow forecast?
A small business should update its 13-week cash forecast weekly. Weekly updates reconcile actual cleared bank transactions, recalibrate accounts receivable collection dates, and maintain rolling 90-day liquidity visibility.
What is the minimum cash reserve a small business should maintain?
A healthy small business should maintain a cash buffer equal to 3 to 6 months of fixed operational expenses. This reserve protects payroll and essential vendor obligations during supply chain bottlenecks or delayed customer collections.
Why is the 13-week cash flow model preferred over a 12-month model?
The 13-week cash flow model aligns directly with one fiscal quarter and provides high-precision weekly visibility into accounts receivable and payroll cycles. In contrast, 12-month models rely on broader monthly estimates that frequently mask short-term liquidity deficits.
What software tools are best for small business cash flow forecasting?
Small businesses commonly use Microsoft Excel or Google Sheets for tailored 13-week forecasting models, or dedicated automated financial platforms such as Float, Helm, Pulse, or QuickBooks Cash Flow Planner that integrate directly with existing accounting software.
-
What is the difference between a cash flow forecast and a cash budget?
A cash flow forecast predicts operational cash movements over a rolling timeline to ensure liquidity, while a cash budget establishes fixed spending limits. Budgets dictate targets, whereas forecasts provide rolling real-world visibility into bank balances.
-
How often should a small business update its cash flow forecast?
A small business should update its 13-week cash forecast weekly. Weekly updates reconcile actual cleared bank transactions, recalibrate accounts receivable collection dates, and preserve an uninterrupted 90-day liquidity horizon.
-
What is the minimum cash reserve a small business should maintain?
A healthy small business should maintain a cash buffer equal to 3 to 6 months of fixed operational expenses. This reserve protects payroll and essential vendor obligations during unexpected market friction or delayed invoice settlements.
-
Why is the 13-week cash flow model preferred over a 12-month model?
The 13-week cash flow model aligns directly with one fiscal quarter and provides granular weekly visibility into operational cash cycles. Twelve-month models rely on aggregated monthly estimates that frequently conceal critical intra-month payroll and payables deficits.
-
What software tools are best for small business cash flow forecasting?
Dedicated financial tools like Float, Helm, and Pulse integrate directly with accounting software, while custom spreadsheets offer complete modeling flexibility. Cloud accounting add-ons sync bank feeds and unpaid invoices automatically to minimize manual data entry errors.