
Insuring a classic or collector car with Hagerty costs between $250 and $650 per year on average, representing a 27% to 33% discount compared to standard daily-driver auto insurance policies. Because collector vehicles are driven strictly for pleasure, logged for fewer annual miles, and stored in secure private garages, specialized underwriters face substantially lower loss frequency. A $20,000 vintage cruiser typically costs roughly $200 to $350 annually, a $50,000 classic muscle car averages $400 to $650, while six-figure exotics and historic prototypes scale from $1,000 to $2,500+ per year.
Unlike standard automotive insurance—which reimburses policyholders based on depreciating Actual Cash Value (ACV)—Hagerty writes policies under a contractually binding Guaranteed Value® (Agreed Value) framework. In the event of a covered total loss, Hagerty pays out the exact agreed dollar figure without depreciation deductions or arbitrary adjuster disputes. Below is the full cost breakdown, valuation tier analysis, underwriting qualifications, and policy endorsement guide for insuring a collector car with Hagerty.
Quick Premium Estimates by Vehicle Agreed Value
- Entry-Level Classic ($10,000 – $25,000): $180 – $350 / year ($15 – $29 / month)
- Mid-Tier Muscle / Sports Classic ($30,000 – $60,000): $350 – $650 / year ($29 – $54 / month)
- Premium Classic / Modern Collector ($65,000 – $100,000): $700 – $1,200 / year ($58 – $100 / month)
- Exotics & High-End Supercars ($100,000 – $250,000+): $1,200 – $2,800+ / year ($100 – $233+ / month)
Why Hagerty Costs Less Than Standard Auto Insurance
Specialty collector vehicle underwriting operates on completely different actuarial risk models than conventional commuter auto insurance. Traditional carriers such as State Farm, GEICO, or Progressive price policies based on high-risk variables: daily highway rush hours, unprotected parking lots, high annual mileage (12,000+ miles), and distracted driving.
In contrast, Hagerty requires proof that every licensed household member has an insured primary daily-driver vehicle. Collector cars covered under Hagerty policies are operated almost exclusively for weekend pleasure touring, car club rallies, parades, and exhibition events. Because these cars average fewer than 2,000 miles per year and sleep in locked garages, collision and vandalism claim frequencies are exceptionally low, allowing Hagerty to slash annual premiums by up to a third.
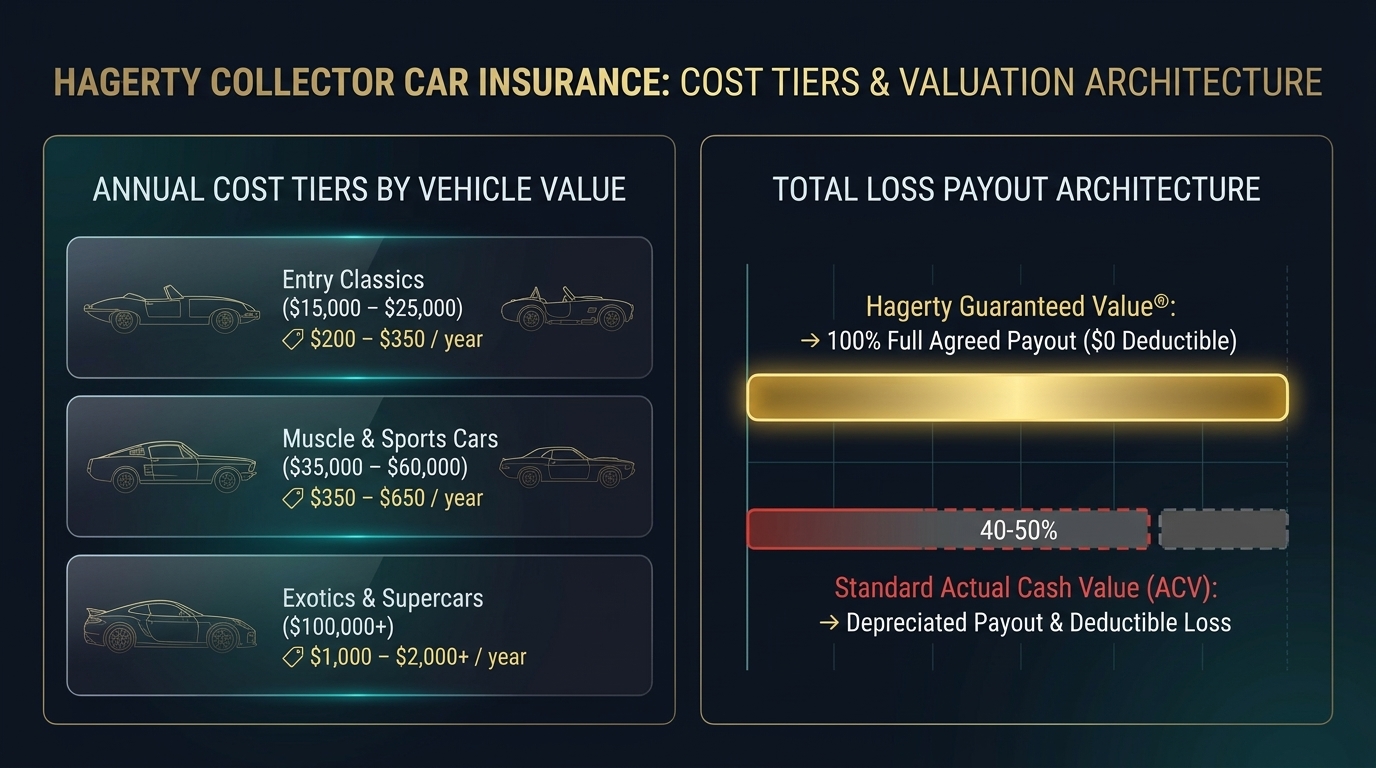
Figure 1: Hagerty collector car cost tiers by valuation and the Guaranteed Value® payout structure.
Hagerty Guaranteed Value® vs. Standard Actual Cash Value (ACV)
The single most important distinction between collector insurance and standard car insurance is how total loss payouts are calculated.
| Policy Feature | Hagerty Guaranteed Value® | Standard Daily Auto Policy (ACV) |
|---|---|---|
| Valuation Method | Mutually agreed market value set upfront | Actual Cash Value minus algorithmic depreciation |
| Total Loss Payout | 100% of agreed value paid in full | Adjuster book value (often pennies on the dollar) |
| Deductible Options | $0 deductible available on most classics | $500 to $1,500 mandatory deductibles |
| Annual Premium | $250 – $650 / year (Typical classic) | $1,200 – $2,400+ / year |
| Vehicle Restoration Coverage | Quarterly value step-ups & spare parts | Excluded or severely limited |
Key Underwriting Criteria: Who Qualifies for Hagerty?
Hagerty maintains specific eligibility gates to preserve low premium pricing across its insured pool. To qualify for collector vehicle coverage, your vehicle and driving profile must satisfy four primary underwriting rules:
- Separate Daily Driver Vehicle: Every licensed driver in your household must own and operate a standard primary vehicle insured with a regular auto carrier. The collector car cannot be used for daily school runs or routine workplace commuting.
- Secure Enclosed Storage: The vehicle must be kept in an enclosed, locked private garage, residential barn, or commercial storage facility when parked at home. Vehicles stored in open carports or street parking are generally ineligible.
- Clean Driving History: Underwriters review Motor Vehicle Records (MVR). Drivers with recent major moving violations, alcohol-related infractions (DUIs), or excessive at-fault accidents within the prior 3 to 5 years face rejection or surcharged tiers.
- Pleasure & Hobby Use: Eligible usage includes pleasure driving, organized club events, exhibitions, parades, cars-and-coffee meetups, and occasional errands. While Hagerty does not impose rigid fixed odometer caps on standard policies, business commercial hauling or commercial ride-sharing is strictly prohibited.
Specialized Endorsements and Add-On Protections
Hagerty offers specialized endorsements tailored to automotive collectors and enthusiasts that standard insurers cannot provide:
- Cherished Salvage®: In the event of a covered total loss, this endorsement allows you to receive your 100% full Guaranteed Value payout and retain ownership of the wrecked chassis without deducting salvage value. This enables collectors to preserve rare serial numbers, body panels, and custom powertrains.
- Spare Parts Coverage: Includes standard protection (typically $750, expandable up to $2,500+) for extra carburetors, original wheels, transmission spares, and specialized garage tools not covered by standard homeowners policies.
- Vehicles Under Active Restoration: Provides automatic quarterly valuation increases (up to 10% per quarter) to safeguard fresh metalwork, custom paint, and replacement components as restoration projects advance.
- Hagerty Drivers Club (Roadside Assistance): Offers specialized flatbed towing with soft straps and low-approach ramps designed to transport lowered exotics and fragile vintage suspensions without frame or bumper damage.
For collectors evaluating enterprise asset protection and technical operations, reviewing our analysis on dealership personnel training standards and our strategic guide to paint preservation and exterior vehicle detailing provides essential operational depth.
Frequently Asked Questions (FAQ)
-
Does Hagerty have a strict annual mileage limit?
No, Hagerty does not enforce a rigid annual mileage cap on standard collector car policies. However, the vehicle must be operated solely for pleasure, exhibitions, club tours, and occasional weekend cruises. If your annual mileage pattern mimics a daily commute, Hagerty may decline renewal or require policy reclassification.
-
Can I daily drive a car insured with Hagerty?
No, you cannot daily drive a vehicle insured under a Hagerty classic policy. Underwriting rules mandate that all licensed household drivers possess a separate regular daily vehicle with standard insurance. Hagerty policies strictly exclude daily commuting, commercial hauling, or ride-share operations.
-
What qualifies as a collector car with Hagerty?
Hagerty insures antique vehicles (25+ years old), classic muscle cars, street rods, exotics, modified imports, and modern collector vehicles. Even modern cars (such as late-model Corvettes, Porsche 911s, or low-production sports cars) qualify provided they are maintained as weekend enthusiast collectibles rather than daily drivers.
-
Does Hagerty offer a $0 deductible?
Yes, Hagerty offers a $0 deductible option for comprehensive and collision coverage on most traditional classic cars. While higher deductibles ($500 or $1,000) are available to further reduce annual premiums, selecting a $0 deductible on a classic vehicle adds very little to the annual policy cost.